
Requirements
- order-matching system for
buyandsellorders. Types of orders:- Market Orders
- Limit Orders
- Stop-Loss Orders
- Fill-or-Kill Orders
- Duration of Orders
- high availability and low latency for millions of users
- async design - use messaging queue extensively (btw. side-effect: engineers work on one service pub to a queue and does not even know where exactly is the downstream service and hence cannot do evil.)
Architecture
Components and How do they interact with each other.
order matching system
- shard by stock code
- order's basic data model (other metadata are omitted):
Order(id, stock, side, time, qty, price) - the core abstraction of the order book is the matching algorithm. there are a bunch of matching algorithms(ref to stackoverflow, ref to medium)
- example 1: price-time FIFO - a kind of 2D vector cast or flatten into 1D vector
- x-axis is price
- y-axis is orders. Price/time priority queue, FIFO.
- Buy-side: ascending in price, descending in time.
- Sell-side: ascending in price, ascending in time.
- in other words
- Buy-side: the higher the price and the earlier the order, the nearer we should put it to the center of the matching.
- Sell-side: the lower the price and the earlier the order, the nearer we should put it to the center of the matching.
x-axis
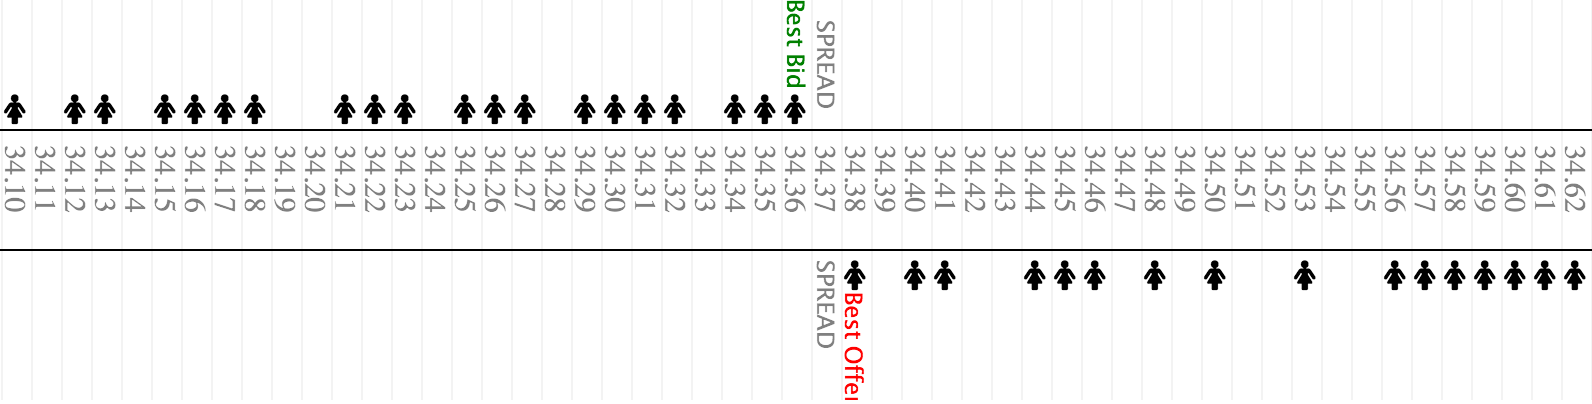
with y-axis cast into x-axis
Id   Side    Time   Qty   Price   Qty    Time   Side
---+------+-------+-----+-------+-----+-------+------
#3                        20.30   200   09:05   SELL
#1                        20.30   100   09:01   SELL
#2                        20.25   100   09:03   SELL
#5   BUY    09:08   200   20.20
#4   BUY    09:06   100   20.15
#6   BUY    09:09   200   20.15
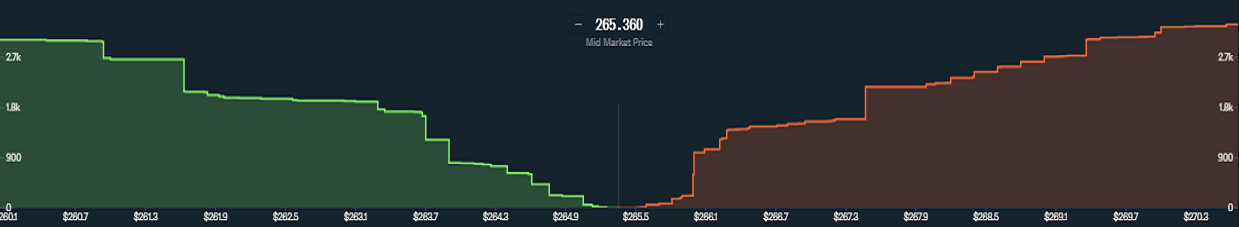
Order book from Coinbase Pro
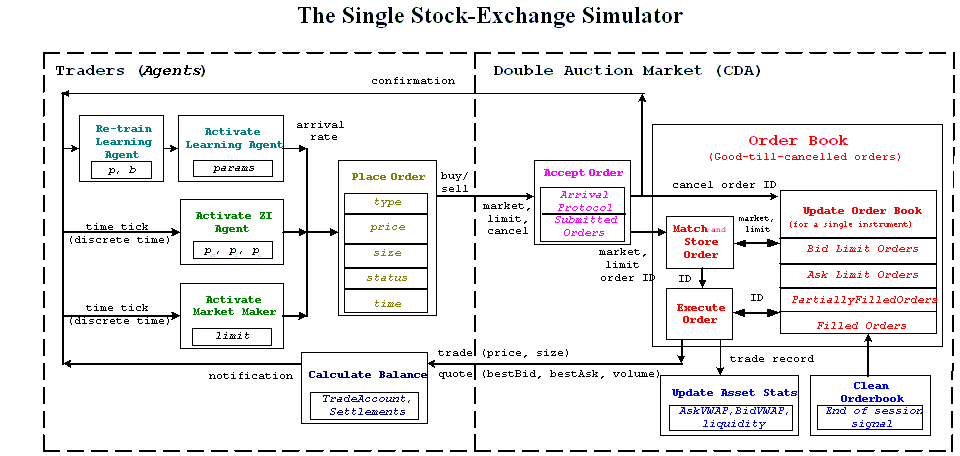
The Single Stock-Exchange Simulator
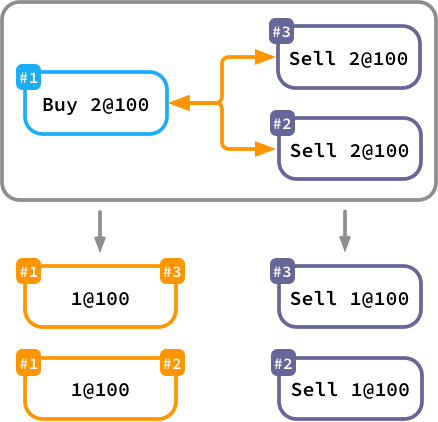
- example 2: pro-rata
How to implement the price-time FIFO matching algorithm?
- shard by stock, CP over AP: one stock one partition
- stateful in-memory tree-map
- periodically iterate the treemap to match orders
- data persistence with cassandra
- in/out requests of the order matching services are made through messaging queues
- failover
- the in-memory tree-maps are snapshotting into database
- in an error case, recover from the snapshot and de-duplicate with cache
How to transmit data of the order book to the client-side in realtime?
- websocket
How to support different kinds of orders?
- same
SELL or BUY: qty @ pricein the treemap with different creation setup and matching conditions- Market Orders: place the order at the last market price.
- Limit Orders: place the order with at a specific price.
- Stop-Loss Orders: place the order with at a specific price, and match it in certain conditions.
- Fill-or-Kill Orders: place the order with at a specific price, but match it only once.
- Duration of Orders: place the order with at a specific price, but match it only in the given time span.
Orders Service
- Preserves all active orders and order history.
- Writes to order matching when receives a new order.
- Receives matched orders and settle with external clearing house (async external gateway call + cronjob to sync DB)
References
- How Exchange Happen? Simulating a financial exchange in Scala
- Open Sources
- The Financial Information eXchange ("FIX") Protocol
- Types of orders: Technical Analysis Course. Training,Coaching & Mentoring for Traders / Investors - Types of orders used when buying or selling a stock
- GitHub - fmstephe/matching_engine: A simple financial trading matching engine. Built to learn more about how they work.
- Automated Algorithmic Trading: Learning Agents for Limit Order Book Trading